01
Trade Risk
Control the amount that can be lost on an individual position.
Learn how algorithmic trading can support risk management through position sizing, stop losses, exposure limits, drawdown controls, monitoring and disciplined execution.
Algorithmic trading does not make a strategy safe by itself. Its real advantage is that clearly defined risk rules can be translated into repeatable actions—helping traders control position size, stop losses, exposure, drawdown and execution without relying entirely on emotion or memory.
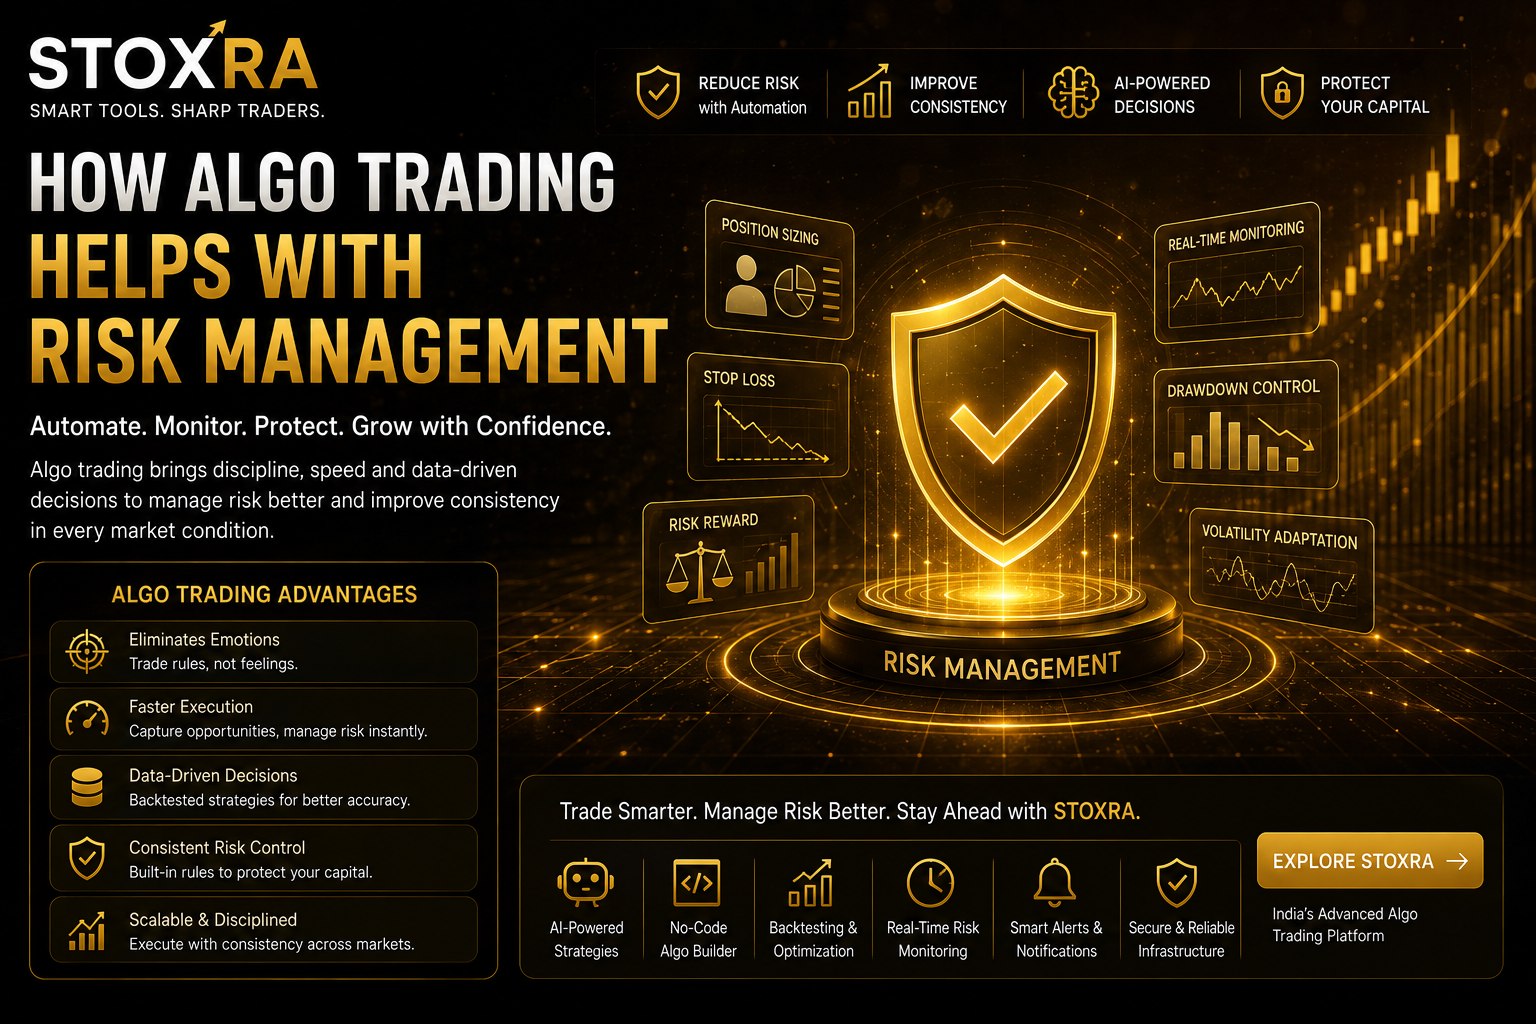
Automation is not risk management. Automation is the mechanism. Risk management comes from deciding how much to risk, when a strategy is invalidated, how much exposure is acceptable, and what the system should do when conditions change.
Manual trading creates several points where human behaviour can interfere with a predefined plan. A trader can move a stop, increase position size after a loss, ignore a daily loss limit or enter a trade because of fear of missing out. An algorithm can reduce some of these behavioural errors by executing rules consistently.
But algorithms can also create new risks. A coding error, bad market-data assumption, API failure, incorrect order logic or poorly tested strategy can turn automation into a faster way to lose money. That is why risk controls must be designed alongside the strategy rather than added at the end.
When a trader manually clicks an order, there is a natural pause between the decision and execution. Automated systems can generate and submit orders much faster and can repeat them many times. That efficiency is useful, but it means a flawed rule can also be repeated at scale.
A robust algorithmic workflow therefore needs controls at several levels: individual trades, strategy exposure, portfolio exposure, daily losses, system health and execution behaviour.
Control the amount that can be lost on an individual position.
Prevent one strategy from accumulating excessive exposure or repeated losses.
Handle data failures, connectivity problems, duplicate orders and unexpected behaviour.
Set risk limits before deployment.
Encode entry, exit and risk rules.
Test behaviour across historical scenarios.
Start with controlled capital and exposure.
Track positions, orders and risk metrics.
Review failures and adjust responsibly.
This sequence is more important than any particular programming language or trading framework. If the risk model is unclear before deployment, adding more automation will not fix the underlying problem.
The simplest benefit of algorithmic execution is consistency. A strategy can have explicit rules for maximum position size, maximum number of open positions, stop-loss placement, daily loss, exposure and trading hours.
| Risk Rule | Example Purpose | System Response |
|---|---|---|
| Max Position Size | Prevent a single trade from dominating the account. | Reject or reduce an order above the limit. |
| Daily Loss Limit | Prevent one bad session from becoming a large drawdown. | Stop opening new trades after the threshold. |
| Max Exposure | Control aggregate capital at risk. | Block additional exposure beyond the defined ceiling. |
| Trading Window | Avoid trading outside intended market conditions. | Disable entries outside configured hours. |
These are examples, not universal settings. Risk limits should be based on the strategy, account, instrument, liquidity and the trader's own risk tolerance.
Position sizing determines how much capital or exposure is allocated to a trade. In a manual workflow, traders can accidentally vary size because of confidence, recent wins or losses. An algorithm can calculate size using a consistent rule.
One simple risk-based framework starts by defining the maximum rupee amount you are willing to lose if the stop is reached.
Position Size ≈ Maximum Planned Loss ÷ Risk per Unit
For example, if a strategy allows a fixed maximum loss per trade and the distance between entry and invalidation is known, the system can calculate an appropriate quantity subject to liquidity, lot-size and instrument constraints.
The formula is not a guarantee of actual loss. Gaps, slippage and execution conditions can cause realised losses to differ from the planned amount.
A stop-loss can be part of an algorithmic risk framework, provided the logic is carefully designed. The important point is not simply "use a stop"; it is deciding what event invalidates the strategy and how the system should react.
A predefined price or percentage level can be used when the strategy is designed around a fixed risk distance.
The invalidation point can be linked to market structure, such as a recent swing level.
Some systems scale risk distance with volatility rather than using the same distance in every market condition.
A rule can adjust protective levels as a position moves, but poorly designed trailing logic can exit too early.
Automation can enforce the rule. It cannot make the rule economically sensible.
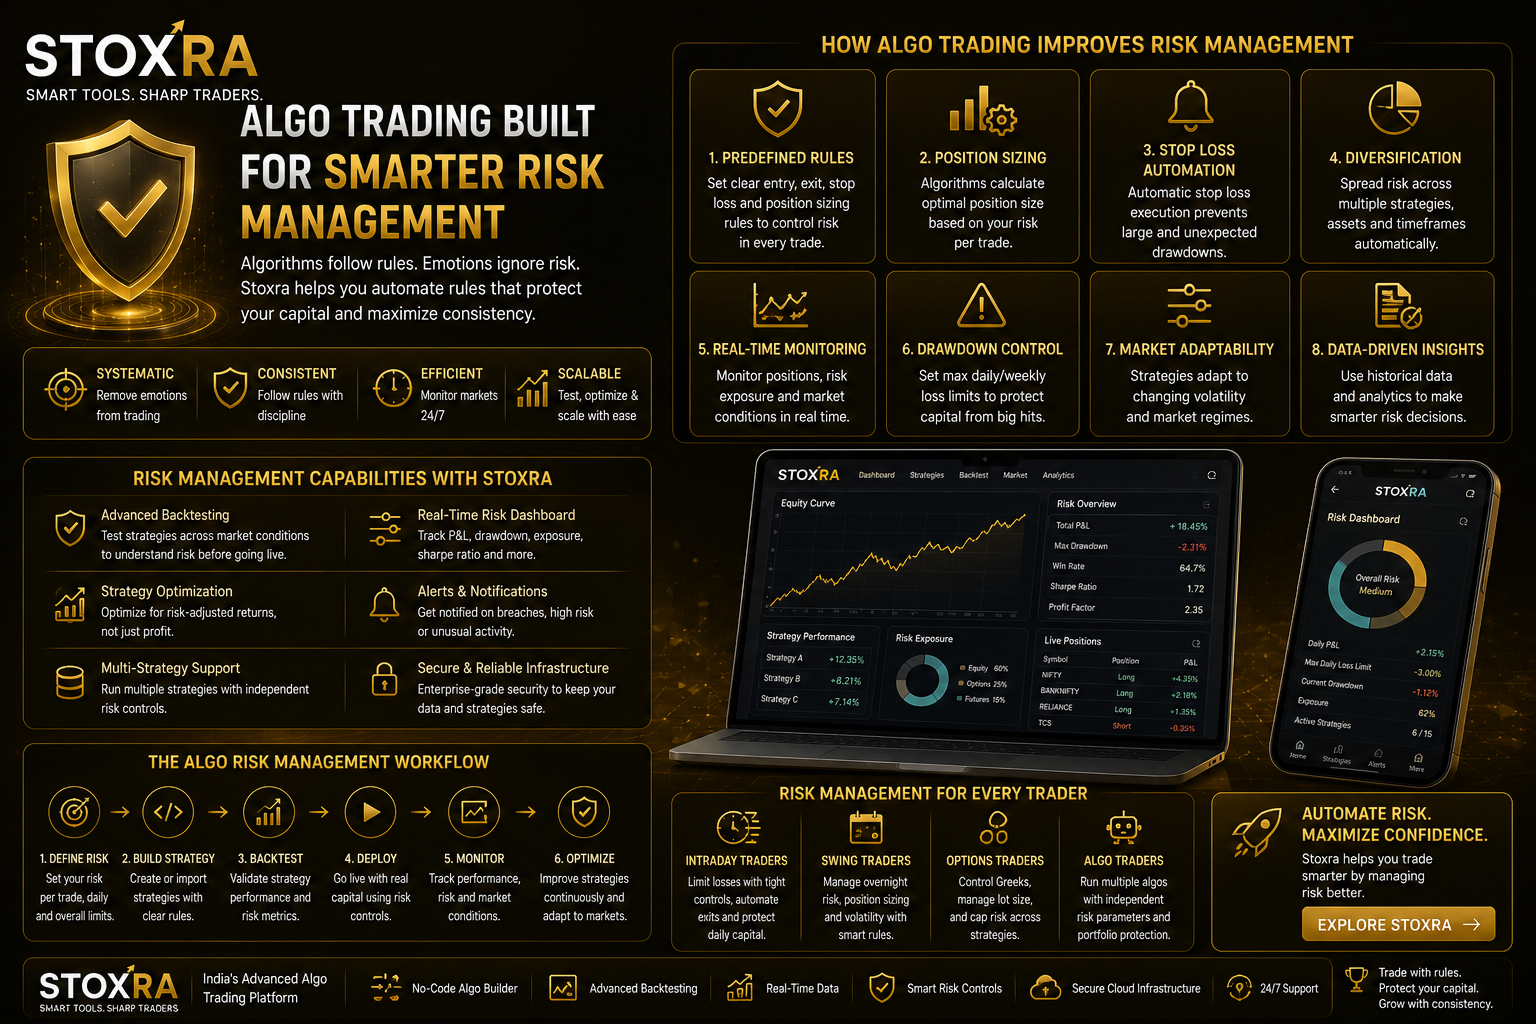
A strategy can have profitable trades and still experience uncomfortable losing periods. Drawdown controls are designed to prevent a strategy from continuing at full exposure after it enters a condition where its historical assumptions may no longer hold.
For a beginner-friendly explanation of loss controls, read Daily Loss Limits for Intraday Trading.
Looking at each trade independently can hide concentration risk. Three different positions can appear diversified by symbol while still being heavily exposed to the same sector, market factor or direction.
Track the combined size of all open positions and strategies.
Consider whether supposedly separate positions tend to move together.
Set limits so one automated strategy does not dominate the portfolio.
Diversification can reduce concentration, but it does not eliminate market risk. During stress, correlations can change and assets that normally behave differently can move together.
Before an automated strategy is deployed, historical testing can reveal how its risk rules behaved across different periods. A useful test should examine more than total return.
| Metric | Question |
|---|---|
| Maximum Drawdown | How severe was the worst historical decline? |
| Win Rate | How often did trades finish profitably? |
| Average Win/Loss | How large were winners compared with losers? |
| Exposure | How much capital or risk was active at one time? |
| Stress Periods | How did the strategy behave during unusual volatility? |
Backtesting is not proof of future performance. It can contain look-ahead bias, survivorship bias, unrealistic fills, overfitting and other errors. Read paper trading vs backtesting for the distinction between simulation approaches.
A good automated system should not simply be capable of sending orders. It should also be capable of stopping itself when defined abnormal conditions occur.
A kill switch or emergency shutdown mechanism can be an important operational control. It should be tested rather than existing only as a button that nobody has ever used.
A backtest may assume that an order is filled exactly at a historical price. Real markets do not always behave that way. Large orders, fast moves, gaps and limited liquidity can create slippage.
Automated systems should therefore account for execution assumptions. A strategy that looks excellent before transaction costs and slippage can look much weaker after realistic assumptions are included.
This is especially important when strategies trade frequently. Even small per-trade costs can accumulate. Algorithmic efficiency should never be confused with economic efficiency.
One of the clearest benefits of rules-based automation is reducing emotional decisions. A system does not feel fear after a losing trade or excitement after a winning streak. If the rules say stop trading after a loss threshold, the system can enforce that rule.
However, removing the trader from every decision is not automatically better. Human oversight is still important for software updates, data quality, broker changes, market structure changes, infrastructure incidents and unexpected system behaviour.
Automate repeatable decisions. Keep humans responsible for the system's assumptions and controls.
| Condition | Potential Algo Response | Risk Consideration |
|---|---|---|
| Normal Volatility | Run the strategy within normal exposure limits. | Monitor whether realised behaviour matches expectations. |
| High Volatility | Reduce position size or tighten exposure rules if designed to do so. | Slippage and rapid moves can increase losses. |
| Low Liquidity | Restrict instruments or order size. | Execution quality can deteriorate. |
| Drawdown | Pause, reduce exposure or trigger a review. | A temporary pause should be based on predefined logic, not panic. |
This distinction is often overlooked. Strategy risk asks whether the trading idea itself can lose money. System risk asks whether the software can behave incorrectly even if the strategy is sound.
Both categories need separate controls. A perfect software system cannot rescue a fundamentally bad strategy, and a good strategy can still be damaged by faulty infrastructure.
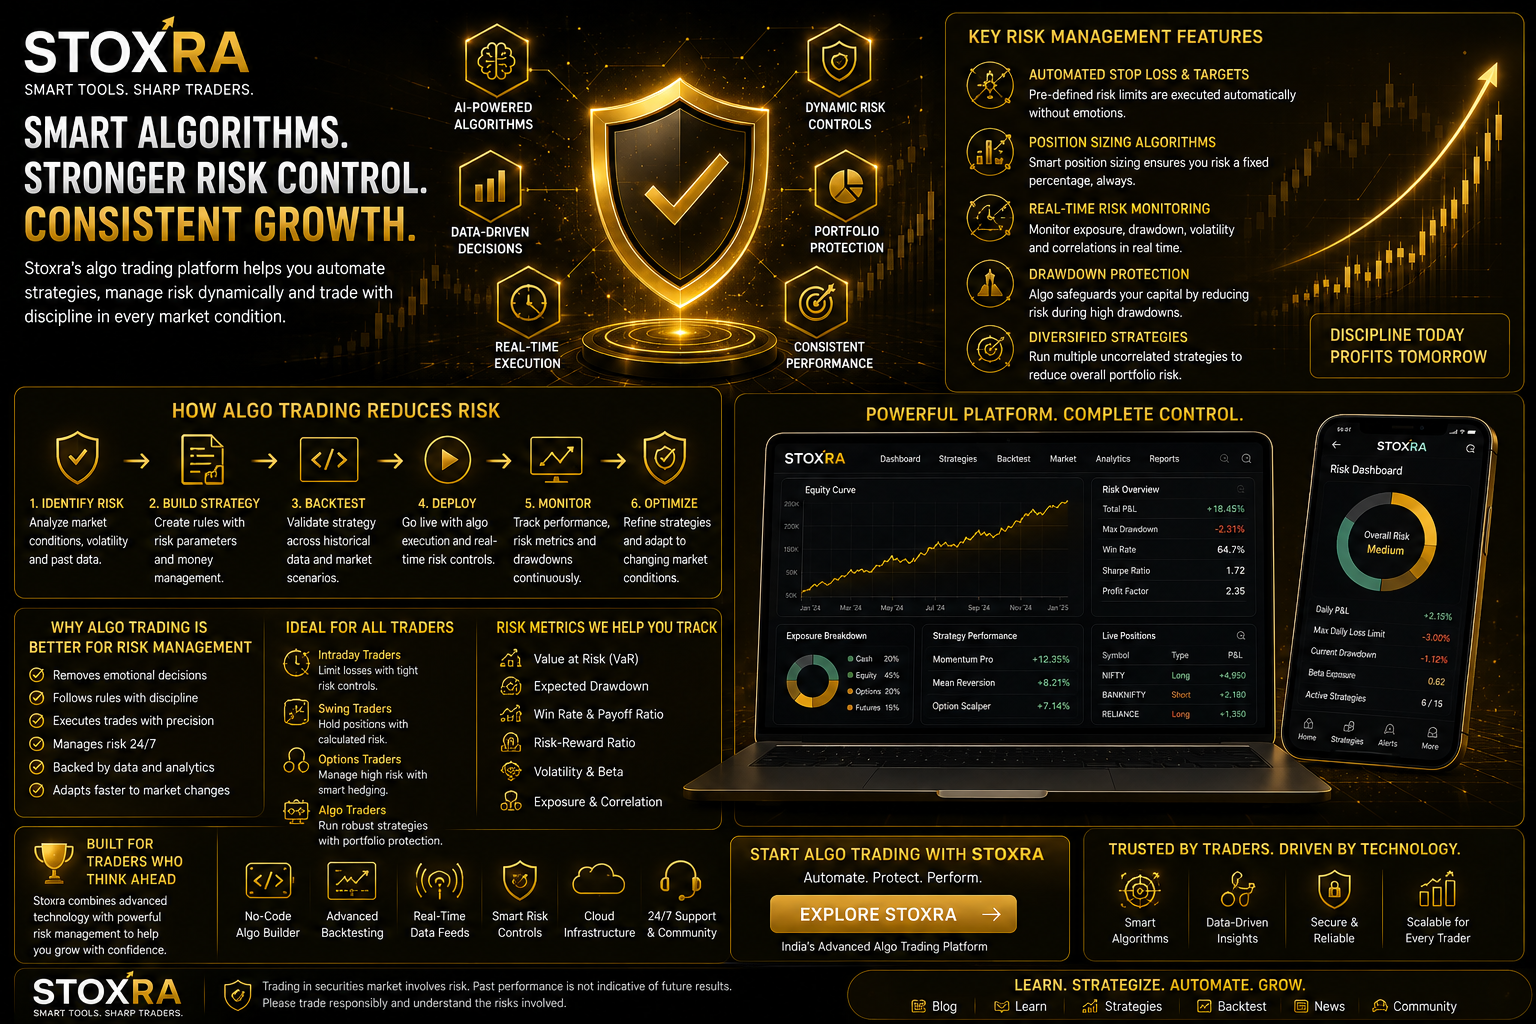
STOXRA's automated trading tools can be explored as part of an algorithmic workflow where strategy rules, execution and risk controls need to work together. The right way to evaluate any platform is to examine the actual features and workflow rather than assuming automation itself makes a strategy safe.
You can also review intraday risk management for beginners and options trading risk management for beginners to compare how risk controls change across trading styles.
For a broader perspective on the relationship between actuarial thinking, data science and risk, see STOXRA's data-science and risk-management article.
Designing risk rules around historical data until the backtest looks unrealistically perfect.
Assuming APIs, data feeds and servers will always behave perfectly.
Letting a system trade indefinitely without exposure limits, alerts or review conditions.
The most dangerous assumption is that a profitable backtest automatically means a safe production system. It does not. Testing, deployment controls and monitoring are separate responsibilities.
No. Algorithms can automate risk controls, but the strategy, assumptions, infrastructure and market itself still carry risk.
It can enforce predefined rules for position size, stop losses, exposure, daily losses, trading windows and other controls consistently.
No. Gaps, slippage, liquidity conditions, execution failures and other events can cause actual losses to differ from planned limits.
Backtesting can show how a strategy and its risk rules behaved across historical data, but it cannot guarantee future results and must account for realistic assumptions.
A kill switch is an emergency mechanism designed to stop or disable automated trading when predefined abnormal conditions or serious system issues occur.
Beginners should first understand the strategy, order mechanics and risk model. Automation should come after the underlying process is understood and tested.
Risk management is connected to every part of an algorithmic trading workflow. Use these related STOXRA guides to go deeper into strategy design, paper trading, execution, technical analysis, options data, AI tools and automated trading.
Good algo trading is not about removing every human decision. It is about converting clearly understood rules into consistent execution while keeping monitoring, testing and risk controls in place.
Explore STOXRA Automated Trading →Strategies · Backtesting · Execution · Monitoring · Risk controls
Advertisement